SMSFs – allocation to international shares

According to the Self-Managed Super Fund (SMSF) statistical report March 2019 published by the Australian Tax Office, Australian listed shares made up approximately 30% ($224 Billion approx) of total SMSF assets while overseas shares and managed funds only made up approximately 1% ($7.6 Billion approx). Well to be honest that statistic is rubbish and the true figure is nearer 10-15%.

Graham Hand on the Cuffelinks website delved deeper in to these figures and found the $1.8 Billion in International shares only represented  direct shares listed on Overseas exchanges and did not include the multitude of managed funds, listed investments like ETFs and LICs and other managed investments.

Why do we stay so close to home and what do we miss out on by doing so:

SMSF investors do seem to have a home bias for a number of reasons

Ease of access

Their preference for direct investing rather than investing   through managed funds tends to mean they favour Australian shares because   investing directly into international shares is complex and harder to access.   Issues may include whether or not to hedge, the type of hedging strategy and   implementation.

Performance history

Australian shares have historically outperformed   international shares over the long term which has influenced many SMSF   investors to be underweight international shares in favour of the better   performing and higher yielding Australian shares.

Quasi global exposure

Some SMSF investors believe that investing in   Australian companies that have a global presence, such as BHP and Rio Tinto,   provide adequate exposure to international economies and investment themes.

High yielding shares with franking credits

Australian shares tend to provide relatively   higher levels of income with franking credits.  This can be an important   source of tax effective income for retirees and pre-retirees. The franking   credits can be used to offset other tax within the SMSF (in the accumulation   phase).

Investor understanding and awareness

A SMSF investor will typically have   a deeper knowledge and understanding of the Australian share market and   companies that make up the market than overseas companies. As a result they   may feel more comfortable investing domestically.

 An excessive home bias has its downside which needs to be considered

Some of these considerations are discussed below:

Concentration of the   domestic market

It is well-known that the Australian share market represents a   small portion of the global universe (around 3% as measured by the MSCI   index). Our share market is highly concentrated in a few sectors and a   handful of companies. The resource and banking sectors comprise over 60% of   our market and the top 10 stocks represent 52% of the index (S&P/ASX 200   Index). The biggest company BHP alone makes up 13% of the index. This is   illustrated in the graph below which shows the extent of over-exposure and   under-exposure of Australian shares in various sectors relative to   international shares.This high level of concentration in Australian shares means   that investors are prone to shocks or underperformance affecting these key   sectors and companies. This may derive from such things as legislative   changes and/or events such as a sharp slowdown in China’s economy.

Impact of currency on   returns

SMSF investors should take into account that a   significant amount of the long-term underperformance of international shares   has been due to the appreciation of the Australian dollar. A rise in the   Australian dollar translates to currency losses which detract from the overall   returns from international assets. To rely on the historical performance of   international shares relative to Australian shares as a guide to future   performance assumes that our Australian dollar will continue to appreciate   over the next few years.

Other domestic investments

SMSF investors that operate a small business and/or own   investment property (either within or outside of their SMSF) already have a   heavy exposure to the direction of the Australian economy. An excessive home   bias to Australian shares in their SMSF exacerbates the extent of their   reliance on the performance of the Australian economy. According to the SMSF   statistical report, 46% of total SMSF assets are either domestic listed   shares or real estate assets.This sort of weighting means SMSF investors are likely to have   a lower level of diversification in their portfolio due to limited exposure   to countries, economies, industries and companies that are either not   available or well represented in Australia. Also, by not investing offshore   the investor has little access to countries with stronger economic growth   prospects than Australia, such as the emerging markets with their rapidly   expanding population and development prospects. It is important to keep in   mind that Australia represents less than 3% of the total world share market.

What is the best way to go about diversifying into international shares?

There are a number of ways of accessing international shares including through the use of managed funds, ETFs, LICs and direct equities with an international focus including those listed on offshore share markets. There are different types of international share funds such as global diversified funds, sector specific funds, market capitalisation funds, country funds and specialist funds.

The best way to access international shares will depend on the investment strategy of the SMSF fund and the amount of money to be placed in international shares. Some guidelines include:

  • SMSF investors with a preference for direct investments may consider buying international ETFs which track an international index or new listed option like MGE which is a close sibling to Magellan’s unlisted Magellan Global Equities fund
  • Investors with a small amount to invest in international shares may prefer a global diversified managed fund that provides broader diversification
  • Investors with a higher risk tolerance and larger amounts of funds may consider a combination of global, diversified funds supplemented with specialist and regional/country funds

Here is a good short video that explains the Home Country Bias well


How investors can deal with currency risk when investing offshore

Currency can pose a significant risk for international investors but it can also provide benefits. When the Australian dollar depreciates, currency gains can be made from the international asset when it is converted back to Australian dollars. Any currency gains will boost returns from the international investment.

Hedging the currency exposure will mean that investors miss out on this gain if the Australian dollar falls. The currency exposure can also add to the diversification benefits of investing overseas. However, if the Australian dollar appreciates the investor will experience currency losses that detract from returns.

Predicting currency movements has proven to be very difficult and is fraught with risk. Nonetheless, if SMSF investors are concerned about the risk of a continued rise in the Australian dollar, they can hedge some or all of their currency risk by the following methods:

  • Investing in a managed fund that actively manages the currency exposure, thereby leaving the hedging decision to the fund manager
  • Investing in a managed fund that has a set amount of hedging in place at all times such as 50% and 100% hedged international share funds
  • Investing in currency ETFs that effectively increase in value if the Australian dollar appreciates, thereby offsetting some or all of the losses made in the international share portfolio.

I hope these thoughts  have been helpful and please take the time to comment.

We can help you determine the right asset allocation for you!

Would love some feedback as well or arrange a meeting by clicking on the Schedule Now

Liam Shorte B.Bus SSA™ AFP

Financial Planner & SMSF Specialist Advisor™

SMSF Specialist Adviser 

 Follow SMSFCoach on Twitter Liam Shorte on Linkedin NextGen Wealth on Facebook   

Verante Financial Planning

Tel: 02 98941844, Mobile: 0413 936 299

PO Box 6002 BHBC, Baulkham Hills NSW 2153

5/15 Terminus St. Castle Hill NSW 2154

Corporate Authorised Representative of Viridian Select Pty Ltd ABN 41 621 447 345, AFSL 51572

This information has been prepared without taking account of your objectives, financial situation or needs. Because of this you should, before acting on this information, consider its appropriateness, having regard to your objectives, financial situation and needs. This website provides an overview or summary only and it should not be considered a comprehensive statement on any matter or relied upon as such.

Property through super in a SMSF – Part 1: Background

PropertyFrom the media hype you should already know that self-managed superannuation funds (SMSFs) can borrow funds to purchase assets, provided the borrowing satisfies certain requirements outlined in the Superannuation Industry (Supervision) Act 1993. This can be a very attractive option for SMSF trustees for a number of reasons.

This is Part 1 of a 3 part series. In this first article, we will look at the background to the limited recourse borrowing arrangements that can be used by SMSFs to invest in an asset, specifically a residential or commercial property.

Limited recourse borrowing arrangements

While the Superannuation Industry (Supervision) Act contains a general prohibition against borrowing, SMSF trustees have been able to borrow to acquire assets since September 2007. The Act was further amended in July 2010 with the introduction of new legislation that clarified the intended operation of the borrowing exemption. The rules around the use of borrowed funds for repair and improvement and what is an acquirable asset were further clarified in 2012.

SMSFs may borrow funds to acquire an asset provided the following conditions are satisfied:

1) Single acquirable asset: The borrowed funds must be used to acquire a single asset or a collection of identical assets that have the same market value (which are together treated as a single asset), which the fund would otherwise be permitted to acquire. A single asset could be a parcel of, for example, 1000 ANZ Bank shares, but a parcel of 500 ANZ Bank shares and 500 Woolworth’s shares would not meet the definition of a single asset.

2) Restriction on improvements: The borrowed funds are not to be used to improve the acquirable asset. The ATO recently confirmed its position in relation to repairs vs. improvements of an asset acquired through a limited recourse borrowing arrangement in Self Managed Superannuation Funds Ruling SMSFR 2012/1. For example, if a fire damages part of a kitchen (e.g. the cooktop, benches, walls and the ceiling), the SMSF trustee could use the borrowed funds to restore or replace the damaged part of the kitchen with modern equivalent materials or appliances, but it could not use the borrowed funds to extend the size of the kitchen (as this would be considered an improvement).

3) Beneficial ownership: The acquired asset must be held on a trust where the super fund holds the beneficial interest in the acquired asset. This requires what is known commonly as a ‘bare trust’ or a ‘custodian trust’ to be registered as on the title as the legal owner. This is one of the reasons why the process can get complicated and is the main mistake made in implementing this strategy without doing the groundwork first.

4) Legal ownership: the documentation makes it very clear that the actual beneficial owner is the trustee of the self-managed super fund. After acquiring this beneficial interest, the SMSF has the right to acquire the legal ownership of the asset once it has repaid in full the lending for the property purchase.

5) Limited recourse rights of lender on default: If the fund defaults on the borrowing, the rights of the lender under the arrangement are limited to rights relating to the acquired asset. In other words, the lender’s rights are limited to repossessing and disposing of the asset to recover funds. The lender cannot recover funds from the superannuation fund’s other assets or undertakings. However it can become common practice for the lenders to seek personal guarantees from the trustees in their private capacity to add a layer of protection for the lender

6) Restriction on replacement assets: The acquired asset can be replaced by another acquirable asset (but only in very limited circumstances). For example, the proceeds of a claim after a fire destroys a four-bedroom home could be used to rebuild a four-bedroom home in a newer style but you could not build three town-houses on the same site using the funds.

Types of property that can be acquired

An SMSF can only borrow money to acquire an asset if it would not be prohibited from investing in that asset directly under the Act. This includes residential units, houses, commercial property like office units, industrial warehouses and a current flavour of the day: 7/11 stores! A SMSF is prohibited from intentionally acquiring an asset from a related party of the fund.

The exception, business real property, must be acquired for market value but there are Stamp duty exemptions in some States liked Section 62A of the NSW Stamp Duties act. Business real property is an interest in real property where the property is used wholly and exclusively in one or more businesses. It does not have to be in your own business but it can be and this is why the strategy has been so popular with business people.

The borrowing structure

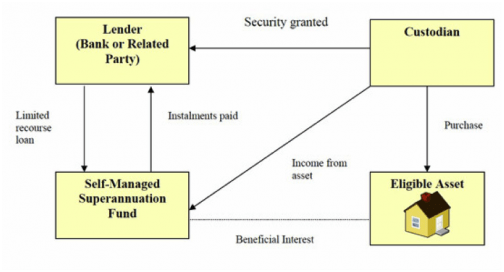
This diagram shows a typical limited recourse borrowing structure:

Borrowing through SMSF

Funding Options

There are two main funding options available:

1) Related party lending: There is no restriction on you, your family, a related trust, or similar entity lending the money to the SMSF. The benefits of this are that you can avoid costly bank legal adviser fees and other incidental costs of borrowing from a bank. You must follow the suggested ‘Safe Harbour Provisions’ outlined in ATO guidance on related party SMSF loans (LRBAs) . You cannot put in place a loan that is worse in commercial terms for the SMSF.

In any self -funding scenario you have to expect greater scrutiny by the auditor and regulators so as to avoid any compliance issues, SMSF members choosing self-funding should ensure their loan to the fund is properly documented and meets the requirements of the SIS Act. For example, the trustee of the SMSF must ensure that all investments are conducted on an arm’s length basis. This means that a proper lease agreement must be in place, repayments must be scheduled and met and as mentioned above the terms of the loan cannot disadvantage the SMSF in comparison to what’s available in the market.

2) Third party lending: Nearly all the major banks, and some specialised non-bank lenders, have developed SMSF loan packages specifically tailored to meet the requirements of the Act. I really do recommend that you seek advice from a broker who has experience in this area as the terms and conditions offered by the various lenders differ dramatically as some deal with them through their residential lending division and others through their commercial divisions.

The bottom line:  Placing real estate assets into your self-managed superannuation fund can be both straightforward and financially sensible, but there are certain rules you need to follow carefully, In the next instalment of our SMSF session we will guide you through the steps involved in the process from start to finish. Please seek independent professional advice to ensure that any proposed strategy complies with the law, because there are severe penalties that can apply if the trustee gets it wrong.

NEXT STEP : THE PROCESS OF BUYING PROPERTY IN AN SMSF (all states are slightly different but follow these steps to ensure you don’t fall foul of the rules)

As always please contact me if you want to look at your own options. You can make an appointment by clicking here. We have offices in Castle Hill and Windsor but can meet clients anywhere in Sydney or via Teams or Zoom or FaceTime .

Liam Shorte B.Bus FSSA™ AFP

Financial Planner & Fellow SMSF Specialist Advisor™


Tel: 02 98993693, Mobile: 0413 936 299

PO Box 6002, Norwest NSW 2153

40/8 Victoria Ave Castle Hill NSW 2154

Corporate Authorised Representative of Viridian Advisory Pty Ltd ABN 34 605 438 042, AFSL 476223

This information has been prepared without taking account of your objectives, financial situation or needs. Because of this you should, before acting on this information, consider its appropriateness, having regard to your objectives, financial situation and needs. This website provides an overview or summary only and it should not be considered a comprehensive statement on any matter or relied upon as such.

Managing the Government Guarantee on Term Deposits as an SMSF Trustee

ID-100264824

SMSF trustees are able to take advantage of cash accounts backed by the Federal Government’s Financial Claims Scheme (FCS), commonly known as the government guarantee, to improve the security of their capital and achieve good levels of interest.

In 2012 the Government announced the guarantee on deposits was to be reduced to a $250,000 cap, down from $1m cap in place since 2008. The lower limit is a concern to many SMSF Trustees given that it reduces competitiveness between the Big 4 banks and smaller the regional banks and the building societies.

The initial reaction especially for the risk averse was for Term Deposits larger than the cap to drift back to the CBA, ANZ, Westpac and NAB, given their much higher credit ratings. They have capitalised on the move and as a consequence we see lower term deposit rates from the Big 4 for amounts more than $250,000 since February 2012.

So what strategies are available to retain the government guarantee and to secure the higher interest rates.  Here are some ideas for the SMSF Trustees and Self funded Retirees to consider:

  1. Do your research on your target providers and consider if the guarantee is really needed. If you are willing to take the risk on the solid backing of many of Australia’s financial institutions. If you are happy with them then you may just opt for the highest interest rate paying one and don’t be afraid to ask them to get you a better deal than advertised as you can get 0.05 to 0.2% by asking! It all adds to your bottom line so don’t be shy.
  2. If you have more than $250,000 to invest, you could split your investment between a number of providers. At www.ratecity.com.au and www.mozo.com.au  they give you details of a number of different institutions such as ING DIRECT, ME Bank, Greater Building Society and Rabobank. Don’t be afraid of these names not being too familiar, they have the guarantee! You could split deposits across 3-4 institutions as well as your current Big 4 favourite and maintain the guarantee on your portfolio.  It does involve a bit of work to set up initially but if you’re wanting a government guarantee, then it’s worth the initial effort, think of it as an Insurance policy application!
  3. The added benefit is that should you need access to some funds urgently then you may only have to break one of the Term Deposits instead of previously breaking the one large one and incurring Break Fee, which we all hate. You may stagger the terms to ensure even more flexibility.
  4. Now you may not be comfortable with this one as the level of knowledge about this sector is not great among individual trustees but you might consider buying some bonds for a higher return. By investing lower in the capital structure in those well-known banks where you are confident that they will continue to trade, you can pick up a higher return. While senior bonds are higher risk than term deposits, the main benefit they have is that they are liquid and can be sold very quickly.
  5. Yields on Australian dollar bonds are not great at the moment as market expectations for a low growth world economy spreads with the IMF this week reducing forecasts even further. Your adviser or fixed interest broker can guide you towards the better risk and decent yielding bonds and you can expect 2.5 to 5.5% for what I would consider suitable risk for a moderately conservative investor if well diversified.
  6. Don’t chase a guarantee or safety to far and limit exposure to underpaying securities like the 10-year government bond, 2.58 per cent. For $50,000, some of the best-paying, three-year term deposits with the deposit guarantee are paying in excess of 3.2 per cent.
  7. If you want diversity without the extra paperwork think about outsourcing this sector to a professional fund manager like Macquarie Income Opportunities Fund. Schroders or Henderson also have decent offerings in this conservative end of the sector. Look for a mindset in a Fund Manager that sees Capital Preservation as a core to their strategy.
  8. Instead of lending to the bank, buy the bank or at least blue chip shares that provide decent dividends. Buy no more than a handful of reliable blue-chip stocks that pay a regular dividend and are forecast to continue to do so through thick and thin. These should be “bottom drawer” stocks. If you have only got a small part of your wealth invested in them then you can afford to let them ride the volatility but you still need to watch their sector for any major changes (think Blockbuster video demise after online streaming). I am talking about the 1 or 2 banks, the consumer staples like Wesfarmers and inflation linked income companies like APA Group which owns Australia’s largest natural gas distribution and storage infrastructure network, constituting mainly gas transmission and distribution, mostly servicing power generation, industrial, and commercial customers.

All to0 hard? Well at Verante Financial Planning we have access to a facility that can access over 20 Term Deposit providers in one place with a one-off application form and easy transfer from institution to institution at maturity for the best rates.Have a look at Australian Money Market

In summary it appears most people are unsure about the future and want guarantees on their investments while on the other side younger people don’t want to take on additional debt at this time. This means we’re likely to see rates remain low for some time. By doing some research and comparing what’s available in the market and maybe seeking advice for a second opinion you can find the Term Deposit that suits your needs.

Are you looking for an advisor that will keep you up to date and provide guidance and tips like in this blog? Then why now contact me at our Castle Hill or Windsor office in Northwest Sydney to arrange a one on one consultation. Just click the Schedule Now button up on the left to find the appointment options.

Liam Shorte B.Bus SSA™ AFP

Financial Planner & SMSF Specialist Advisor™

SMSF Specialist Adviser 

 Follow SMSFCoach on Twitter Liam Shorte on Linkedin NextGen Wealth on Facebook   

Verante Financial Planning

Tel: 02 98941844, Mobile: 0413 936 299

PO Box 6002 BHBC, Baulkham Hills NSW 2153

5/15 Terminus St. Castle Hill NSW 2154

Corporate Authorised Representative of Viridian Select Pty Ltd ABN 41 621 447 345, AFSL 51572

This information has been prepared without taking account of your objectives, financial situation or needs. Because of this you should, before acting on this information, consider its appropriateness, having regard to your objectives, financial situation and needs. This website provides an overview or summary only and it should not be considered a comprehensive statement on any matter or relied upon as such.

Image courtesy of Stuart Miles at FreeDigitalPhotos.net

Five pointers to consider when looking at dividend investing

Ok so you are looking to get back in to the market or use the current dip to add to your portfolio and everyone in every article is saying look for Yield! Well how do you do that or how  do you explain it to a client? I found this article on Morning Star and it was very easy to read and understand so I thought it would be appropriate to pass it on. It discuss 5 points to consider when looking a Dividend Investing:

  1. Look at the past and future – where have dividends come from in the past and can the company sustain them into the future.
  2. Look behind the yield – why is the yield high. Is it because the capital value has fallen or because dividends increasing over time. Capacity to grow its dividends is essential.
  3. Look closer at cyclical stocks – Cyclical companies like Newcrest Mining (NCM) may also have a tendency to pay sporadic dividends and you do not want to be buying into a story that will change in the short-medium term. Again consistency and future capacity are the core.
  4. Look beyond banks – don’t get overexposed to one sector . Look at consumer staples (MTS, WOW, WES), Healthcare, Infrastructure all defensive high yielding sectors. Because the Global financial Crisis revolved around banking, this sector has been more volatile in the recent past and looks to continue in this vein for years to come.
  5. Look for tax implications – what is useful for one type of investor is not for another. Franking Credits are the “CREAM” for a SMSF Pension Investor but of little or no use to someone on a higher Tax Bracket. Look at the after tax implications of an investment for your particular circumstances

So as I said some good points to consider and if you want to read the article in full please go to Click here

Liam Shorte B.Bus SSA™ AFP

Financial Planner & SMSF Specialist Advisor™

SMSF Specialist Adviser 

 Follow SMSFCoach on Twitter Liam Shorte on Linkedin NextGen Wealth on Facebook   

Verante Financial Planning

Tel: 02 98941844, Mobile: 0413 936 299

PO Box 6002 BHBC, Baulkham Hills NSW 2153

5/15 Terminus St. Castle Hill NSW 2154

Corporate Authorised Representative of Viridian Select Pty Ltd ABN 41 621 447 345, AFSL 51572

This information has been prepared without taking account of your objectives, financial situation or needs. Because of this you should, before acting on this information, consider its appropriateness, having regard to your objectives, financial situation and needs. This website provides an overview or summary only and it should not be considered a comprehensive statement on any matter or relied upon as such.

How to react to this volatility as a SMSF Trustee / Investor.

The volatility over the last 6 months has been staggering but it is not unusual in historical terms as it has happened many times before. The difference now is that we are bombarded through all the forms of media with the daily movements of our investments and you just cannot ignore that weight of news. Also many people are now able to take more control of their investments via their own Self Managed Super fund or retail Master Trust / Wrap account.

It’s enough to make an anxious investor abandon shares entirely. But if you jettison equities from your portfolio in favour of cash, bonds and term deposits, it will take you much longer to reach your savings goals, and you may not get there at all.

When you look at current interest rates as being a pretty good predictor of what bonds/fixed interest will return in the future, the outlook isn’t particularly good with the 3yr bond yield hovering around 3.87% and inflation tickling the 3% band.

Likewise, interest rates from term deposits and high interest cash accounts have been dropping sharply in the last 2 weeks with 4s and 5s now in front of 6 month rates where 6s were common last month and forecasters now looking at rate cuts in October.

While short-term fluctuations in the market can be unnerving, they rarely affect long-term returns, for example investors who moved their savings into cash at the end of 2008 and stopped contributing to their superannuation accounts now have an account balance worth 20% less than investors who remained in the market.

With no end to volatility in sight, how do you keep your head while all around you are losing theirs? Here are some coping strategies:

Rebalance, Rebalance, Rebalance. Volatile markets can distort your portfolio. For example, if your goal is to have 35% of your savings in Australian equities, 20% in International Equities, 10% in property, 25% in Fixed Interest and 10% in cash, a big market meltdown could increase the amount you have in Fixed Interest and lower your allocation in equities and property.

To rebalance, you should sell some of your best-performing funds (fixed Interest, bond and cash funds) and put the money in your worst performers, something many investors lack the fortitude or commitment to do. We all know in theory what we’re supposed to do, but in reality do the opposite and flee to the best performer or cash. I know it hurts but you have to understand market cycles as opposed to “herd mentaility”. Look at Warren Buffet this week investing $5 Billion in Bank of America when most were fleeing the stock. He has a strong track record of buying when stocks are out of favour with the mainstream.

Don’t be blind to significant changes in markets like the rise of Asia or the risk of sovereign debt. Look out for changing trends like the move towards income orientated stocks. Your adviser should be pointing these matters out to you and identifying strategic asset allocations to allow for them.

How often should you rebalance? We recommend conducting regular portfolio reviews every six months, but only rebalancing when your allocation is at least 5 percentage points way from your benchmark.

Revisit you long term strategy and stick to it.  If the thought of rebalancing makes your palms sweat, consider investing your savings a “life cycle” strategy. This name for the common strategy, which has become much more popular in the last decade, invests in a mix of shares, bonds and cash and gradually become more conservative as you approach retirement. It is nothing new and most advisers will adjust your portfolio this way as part of your overall strategy but maybe you have not discussed this with them for awhile and the volatility may have led to inaction. Well now is the time to consider your future strategy and get that down in writing so you and your adviser are clear on your objectives, timelines and changing strategy over time.

Resist chasing this year’s ‘winner’ is just as likely to be next year’s ‘loser’. Even during the darkest days, some investments will shine. Lately, the flavour of the day has been gold, which is up considerably this year vs. a decline of almost 9% for the All Ordinaries.

The rise of exchange traded funds and similar products in the past few years has made it easier for small investors to invest in “hard” assets, such as gold and other commodities. In small doses, such investments can diversify your portfolio, but they’re easily abused. For example, while gold has been a winner this year, it’s not for the fainthearted. Factoring in inflation, it would have to reach $2,113 an ounce to reach its 1981 high of $850. That was a long time in the doldrums in between its peaks!

Have a look at the Russell Long Term Investment Returns report for more insight in to this subject. http://www.russell.com/AU/_pdfs/market-reports/asx/ASX_Report_2011.pdf

Save more. In this uncertain world, the amount you save is one of the few things you can control. If your employer matches super contributions or you take advantage of the Government co-contribution fro you or your spouse, you’re guaranteed an investment return — something even gold can’t deliver.

If you look back at just how complicated and volatile the last 10 years have been, people who diversified and rebalanced and kept contributing are well ahead of where they were a decade ago.

Liam Shorte B.Bus SSA™ AFP

Financial Planner & SMSF Specialist Advisor™

SMSF Specialist Adviser 

 Follow SMSFCoach on Twitter Liam Shorte on Linkedin NextGen Wealth on Facebook   

Verante Financial Planning

Tel: 02 98941844, Mobile: 0413 936 299

PO Box 6002 BHBC, Baulkham Hills NSW 2153

5/15 Terminus St. Castle Hill NSW 2154

Corporate Authorised Representative of Viridian Select Pty Ltd ABN 41 621 447 345, AFSL 51572

This information has been prepared without taking account of your objectives, financial situation or needs. Because of this you should, before acting on this information, consider its appropriateness, having regard to your objectives, financial situation and needs. This website provides an overview or summary only and it should not be considered a comprehensive statement on any matter or relied upon as such.

Are we crazy to invest overseas?

Unless you have been in limbo for the last 10 years, you would have noticed that the Australian share market has outperformed international markets over the past decade. Australian shares have outperformed while the US and Europe have been like a quagmire slowly sucking up and depleting our investment funds. SMSF funds have traditionally had a low exposure to this sector and that has paid off in the last 10 years but prior to 2000 it meant they were underperfoming. Has the time come to look at this sector again with potential for another significant drop in the Aussie dollar over the next few years and stellar returns on international funds  as well as improved outlook for the US and Europe as our economy slows? International Investing

The  question for investors is “why should we invest our savings anywhere else other than Australia?  Time to look deeper into an explanation of why Australia has done so well and can it continue or do we need to be looking ahead of the pack for likely changes.

I read recently on the Motley Fool website a warning about false statements like “Diversification is the monster that needs stabbing, because world markets are actually becoming more closely correlated to our home markets, not less”. If this was true then why would we take on currency risk and invest internationally?

Fund managers, asset consultants and financial advisers maintain that good asset allocation is the biggest key to long-term investment returns. However, looking at the ASX200, we realise immediately that our Banking(financial services) and Mining & Resources(20%) sector account for 52% of our index. In comparison, the commonly used benchmark S&P500 only has 30% in these two sectors.

This huge bias is the key reason for the outperformance over the past decade as both of these sectors have had strong returns. The banks prospered through low international borrowing costs and massive consumer driven spending financed through increased household debt while the Chindia (China & India ) story was and still maybe the basis for resources growth here in the “lucky country”. This bias also provides greater risks and when the resources/commodities boom ends and/or our residential housing sector slows down, investors will truly need to think twice about having their money so heavily invested in these two sectors. Now don’t kill the messenger or rush to argue, I am not saying its imminent or that these are poor investments but the markets do go in cycles and better to be ready than blind. Even for a long-term investor you need to choose your entry and exit points in to any investment and while I don’t recommend trying to time markets, neither do I recommend ignoring historical trends and experiences of past cyclical highs and lows!

This is one of the big reasons why it is still important to allocate a certain percentage to international markets. I look for funds and investments that are easy to explain and one of those for example is the Magellan Global fund that invests in global household names like Ebay, Microsoft, Yum Brands (owner of KFC and Pizza Hut) and Novartis (global drug company owns brands like Voltaren and Ritalin). These are brands we all know and use and what is more important, the emerging middle classes in China, India and South America will aspire to obtain their products , so I can see where their current income and future earnings growth will come from.

I wish I knew the exact time when Australian markets would start to underperform and when international investments would pay off  but no one can be certain and by the time it becomes “blatantly obvious” we probably will have missed the boat, so I continue a strategy of diversification with a allocation into international funds with a proven record of  investing in companies with consistent earnings and potential for income growth over the long-term.

Liam Shorte B.Bus SSA™ AFP

Financial Planner & SMSF Specialist Advisor™

SMSF Specialist Adviser 

 Follow SMSFCoach on Twitter Liam Shorte on Linkedin NextGen Wealth on Facebook   

Verante Financial Planning

Tel: 02 98941844, Mobile: 0413 936 299

PO Box 6002 BHBC, Baulkham Hills NSW 2153

5/15 Terminus St. Castle Hill NSW 2154

Corporate Authorised Representative of Viridian Select Pty Ltd ABN 41 621 447 345, AFSL 51572

This information has been prepared without taking account of your objectives, financial situation or needs. Because of this you should, before acting on this information, consider its appropriateness, having regard to your objectives, financial situation and needs. This website provides an overview or summary only and it should not be considered a comprehensive statement on any matter or relied upon as such.